
When a Product Stops Moving, Users Start Looking
Loom built its reputation on a simple promise: record your screen, share a link, skip the meeting. For a few years, that was enough. The product spread through startups and remote teams the way Slack once did – person by person, team by team, until it felt like infrastructure. Then Atlassian acquired it in late 2023 for $975 million, and something shifted. Not dramatically, not loudly. But the roadmap slowed, the product started feeling static, and enterprise buyers who had grown dependent on async video began quietly asking what else was out there.
Descript had been building something adjacent for years – a video and audio editor positioned mostly around podcasters and content creators. But the company has spent the past 18 months making a deliberate push toward workplace video, and the timing couldn’t have been better. Loom’s stagnation created an opening, and Descript is walking through it with a fuller feature set, a more aggressive pricing posture, and a product philosophy that treats video as something worth editing, not just recording.
What Loom Lost After the Atlassian Deal
Acquisitions slow products down. That’s not cynicism – it’s operational reality. When a startup gets absorbed into a larger organization, the product team stops shipping on startup cadence and starts aligning to corporate planning cycles. Loom’s development pace after the Atlassian deal became noticeably more cautious. Features that had been rumored – better analytics, deeper CRM integrations, more granular permissions for enterprise admins – either arrived late or didn’t arrive at all. The AI-powered filler word removal and auto-transcription tools Loom rolled out felt more like table stakes than differentiation by the time they launched.
Enterprise buyers notice this. When a tool they’ve embedded in onboarding flows, sales processes, and internal documentation stops evolving, it creates friction between what the product does and what the team actually needs. IT administrators managing Loom across hundreds of seats started flagging the same complaints: limited admin controls, inconsistent playback reliability, and a pricing structure that felt misaligned with how large teams actually use async video. Atlassian’s enterprise credibility didn’t automatically transfer to Loom. If anything, it made buyers expect more while the product delivered less.
Descript’s Unexpected Enterprise Play
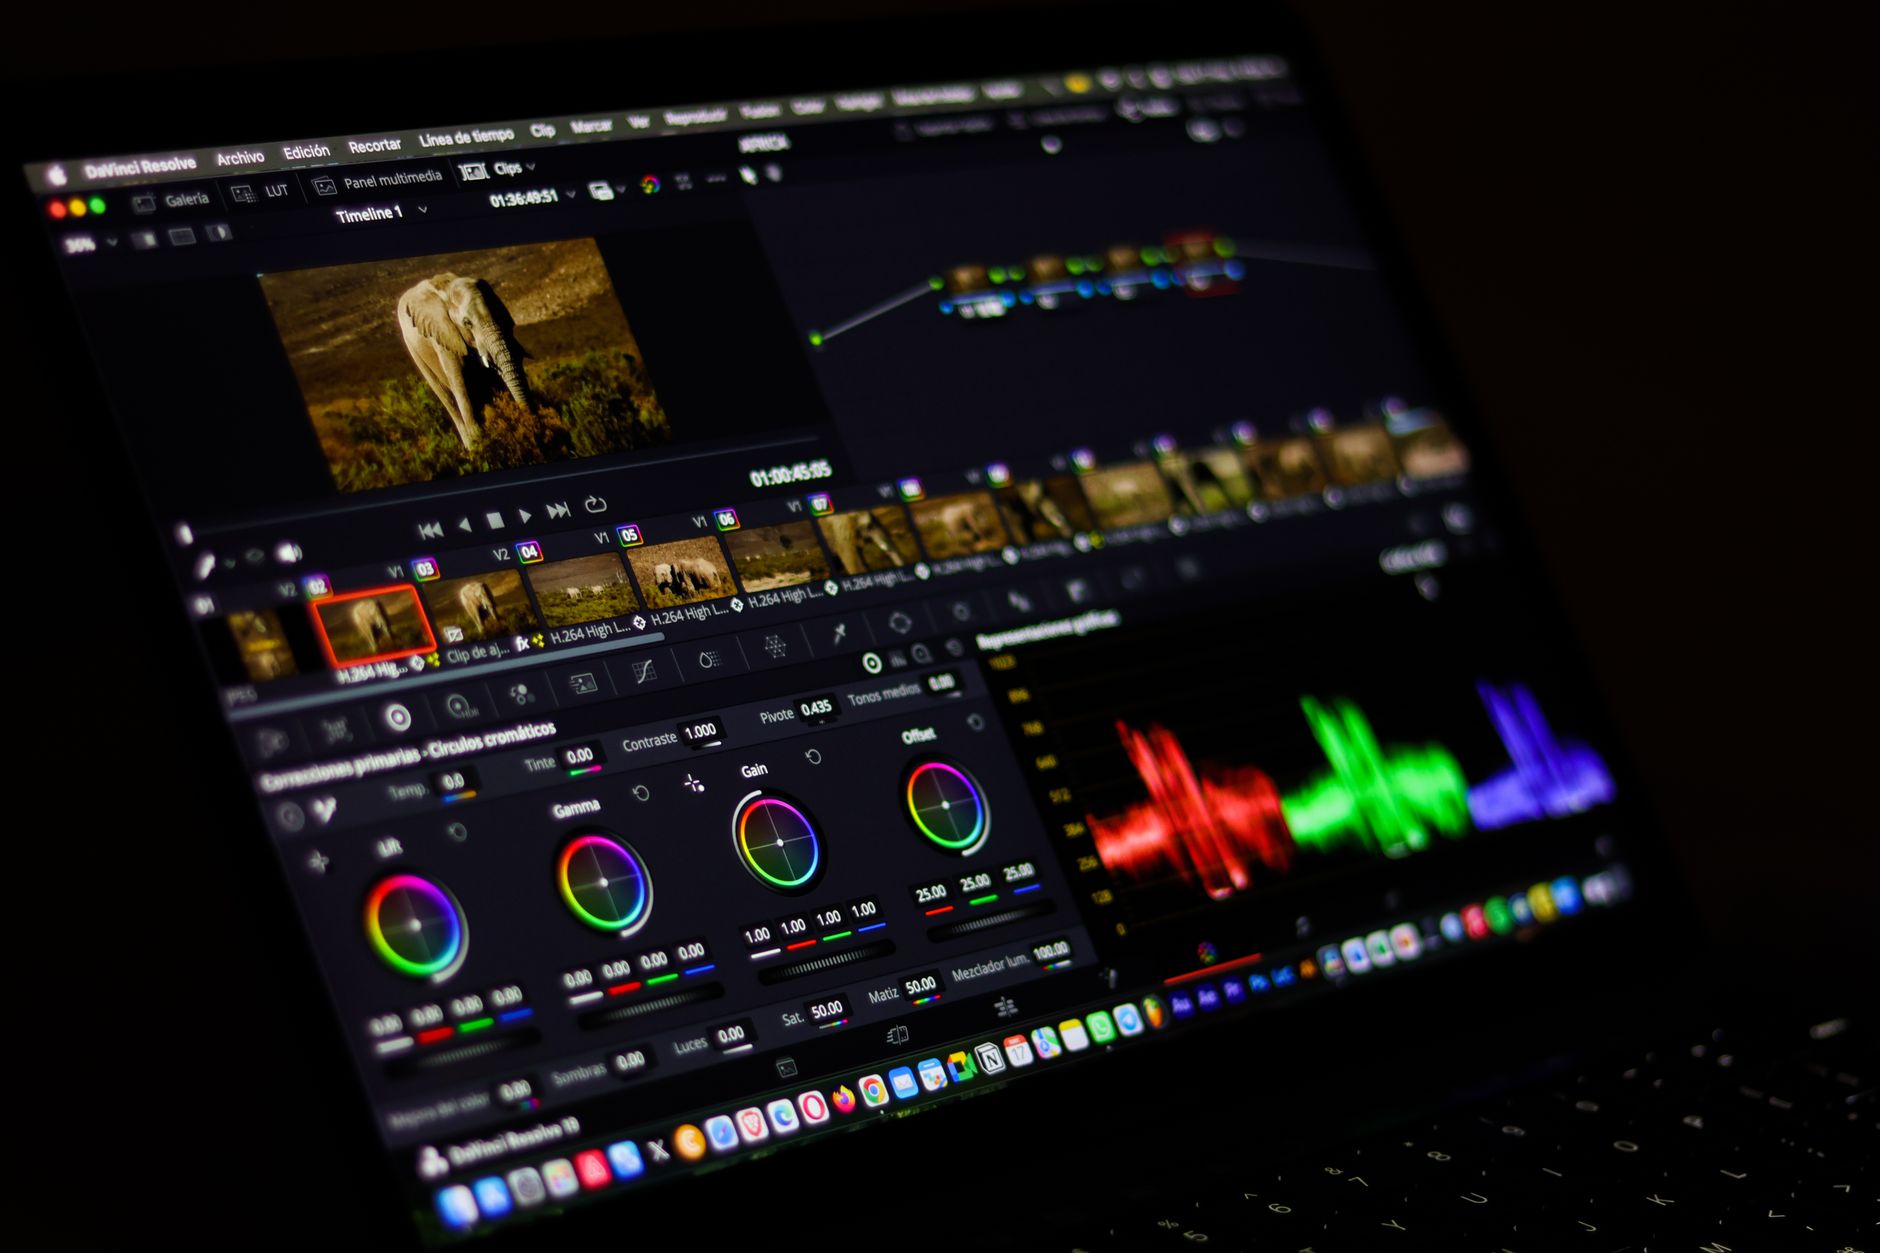
Descript’s core strength has always been its editor. The idea that you can edit video by editing a transcript – deleting words on the page to cut footage, correcting audio by typing new text – is genuinely useful and genuinely different from anything Loom offers. That capability was originally aimed at podcasters and YouTube creators, but it maps remarkably well onto enterprise use cases: polished internal communications, training videos, product demos, and customer-facing content that can’t afford to look rough.
The company has been quietly building out the features that enterprise teams care about. Team workspaces, shared asset libraries, publishing workflows with approval steps, and tighter integration with the tools product and marketing teams already live in. These aren’t glamorous features. They don’t make for exciting launch announcements. But they’re the features that determine whether an IT buyer signs a 500-seat contract or walks away.
Pricing is where Descript is making its sharpest argument. Loom’s enterprise tier is expensive relative to what it delivers at scale, and organizations running large async video programs have started doing the math. Descript’s per-seat costs, combined with the depth of editing capabilities included at each tier, make a credible case that you’re getting more for your spend – especially if your team is producing video content that needs to look intentional rather than improvised.
There’s also a philosophical difference in how each product frames video. Loom treats recording as the destination. You capture something, you share it, you’re done. Descript treats recording as a starting point. That difference matters more than it sounds, because enterprise teams increasingly need video that can be repurposed – turned into documentation, clipped for training materials, archived with searchable transcripts. Loom’s model doesn’t support that workflow. Descript’s does by default.
The Enterprise Displacement Pattern
This kind of quiet competitive displacement follows a recognizable pattern in B2B software. It rarely starts with a dramatic product failure. It starts with a competitor solving one problem better, then another, until the incumbent’s advantage – usually the size of its installed base – stops being enough to retain customers through renewal cycles. Loom’s installed base is still large. Its brand recognition in async video remains strong. But brand recognition doesn’t survive multiple renewal cycles if the product isn’t keeping pace with what buyers need.
The sales motion Descript is running into this environment is straightforward: target teams that already have Loom, demonstrate the editing and collaboration features that Loom lacks, and win at renewal. It’s patient, unglamorous work, but it’s effective. Product-led growth strategies built around individual users converting to paid plans are slower in enterprise; displacement strategies built around renewal timing are faster, and Descript appears to understand that.
What This Means for the Async Video Market
The async video category never fully consolidated after remote work normalized it. Loom had the clearest lead, but the market never stopped attracting competitors. What’s different now is that the competitive pressure is coming from tools that aren’t just trying to clone Loom – they’re trying to build something with higher utility and broader use cases. That’s a harder pitch to defend against because it doesn’t just target dissatisfied users; it targets users who want more than what any screen recorder can offer.
Atlassian’s bet when it acquired Loom was presumably that integrating async video into the Confluence and Jira ecosystem would make the product stickier for enterprise customers already in the Atlassian stack. That integration has been slower to materialize than expected, and in the meantime, enterprise buyers are evaluating standalone options with fresh eyes. Descript isn’t the only challenger in this space – tools like Veed, Synthesia, and others are also pushing into workplace video from different angles. But Descript is positioned closest to Loom’s core use case while offering meaningfully more on top of it.
The more interesting question is whether Atlassian will respond by accelerating Loom’s roadmap or by leaning harder into the platform integration story. A product that becomes truly native to Confluence – where video and documentation exist in the same workflow without friction – would be genuinely difficult to displace. But that product doesn’t exist yet, and Descript isn’t waiting around to find out if it ever will.
Enterprise contracts don’t switch overnight. But they do switch at renewal, and renewal cycles in SaaS are measured in months, not years. Every quarter that Loom ships incrementally rather than meaningfully is another quarter of Descript sales conversations that end with a signed contract.
The real tell will be whether Atlassian treats Loom as a product it’s building or a feature it acquired.
Frequently Asked Questions
Why are enterprise teams switching from Loom to Descript?
Loom’s development pace slowed after its Atlassian acquisition, leaving enterprise buyers with limited admin controls and few new features. Descript offers deeper editing capabilities and more flexible team workflows at competitive pricing.
What makes Descript different from Loom for business use?
Descript lets users edit video by editing a transcript, supports approval workflows, and treats video as content to be refined and repurposed – not just recorded and shared. That depth is what enterprise teams building training or documentation content need.